In Spain, the obligation to insure a vehicle is not tied to whether you drive it, but to whether it exists on the official register. A car sitting untouched in a private garage still legally requires insurance, and the fine for going without can reach several thousand euros, applied even when the vehicle never moves. For newcomers arriving from countries where insurance attaches to active use, this is one of the most common and most expensive misunderstandings. This guide explains exactly how compulsory car insurance in Spain works in 2026, what it costs, what it does and does not cover, and what actually happens, step by step, if you are caught driving, or simply owning, an uninsured car.
The Law: Insurance Follows the Vehicle, Not the Journey
The legal foundation is Royal Legislative Decree 8/2004, the consolidated law on civil liability and insurance for motor vehicles. Its Article 2 states that every owner of a motor vehicle with its habitual base in Spain must take out and keep in force an insurance policy covering civil liability, for each vehicle they own. The key phrase is “keep in force”: the duty is continuous and attached to ownership, so it does not switch off when the car is parked.
This is why a vehicle registered with Spain’s traffic authority (the DGT) must be insured even if it never leaves the driveway. The only ways to lawfully stop paying for insurance are to formally deregister the vehicle, either a temporary deregistration (baja temporal) or a permanent one (baja definitiva), through the DGT. A car on baja temporal does not need insurance, but it also cannot be parked on or driven on public roads; it must be kept off the public highway entirely. Simply cancelling the policy and leaving the car on the street is precisely the situation the law penalises.
What the Compulsory Policy Actually Covers
The legal minimum in Spain is third-party civil liability insurance (responsabilidad civil), and it is important to understand what that protects, because it is narrower than many drivers assume.
Compulsory civil liability covers the damage you cause to others: injuries to other people and damage to their property, up to very high statutory limits (in the tens of millions of euros for personal injury and millions for material damage per claim). What it does not cover is equally important: it does not pay for damage to your own vehicle, nor for your own injuries as the at-fault driver, nor for theft, fire, or weather damage to your car. Those risks require higher tiers of cover, which are optional in law but often sensible in practice.
Spanish insurers typically structure their products in three ascending levels:
- Terceros (third-party): the compulsory civil liability minimum, sometimes bundled with basic extras like legal defence or occupant cover.
- Terceros ampliado (third-party plus): adds cover for specific risks to your own car, commonly theft, fire, and broken glass, without covering your own collision damage.
- Todo riesgo (fully comprehensive): covers damage to your own vehicle too, including at-fault collisions, sometimes with an excess (franquicia) you pay per claim.
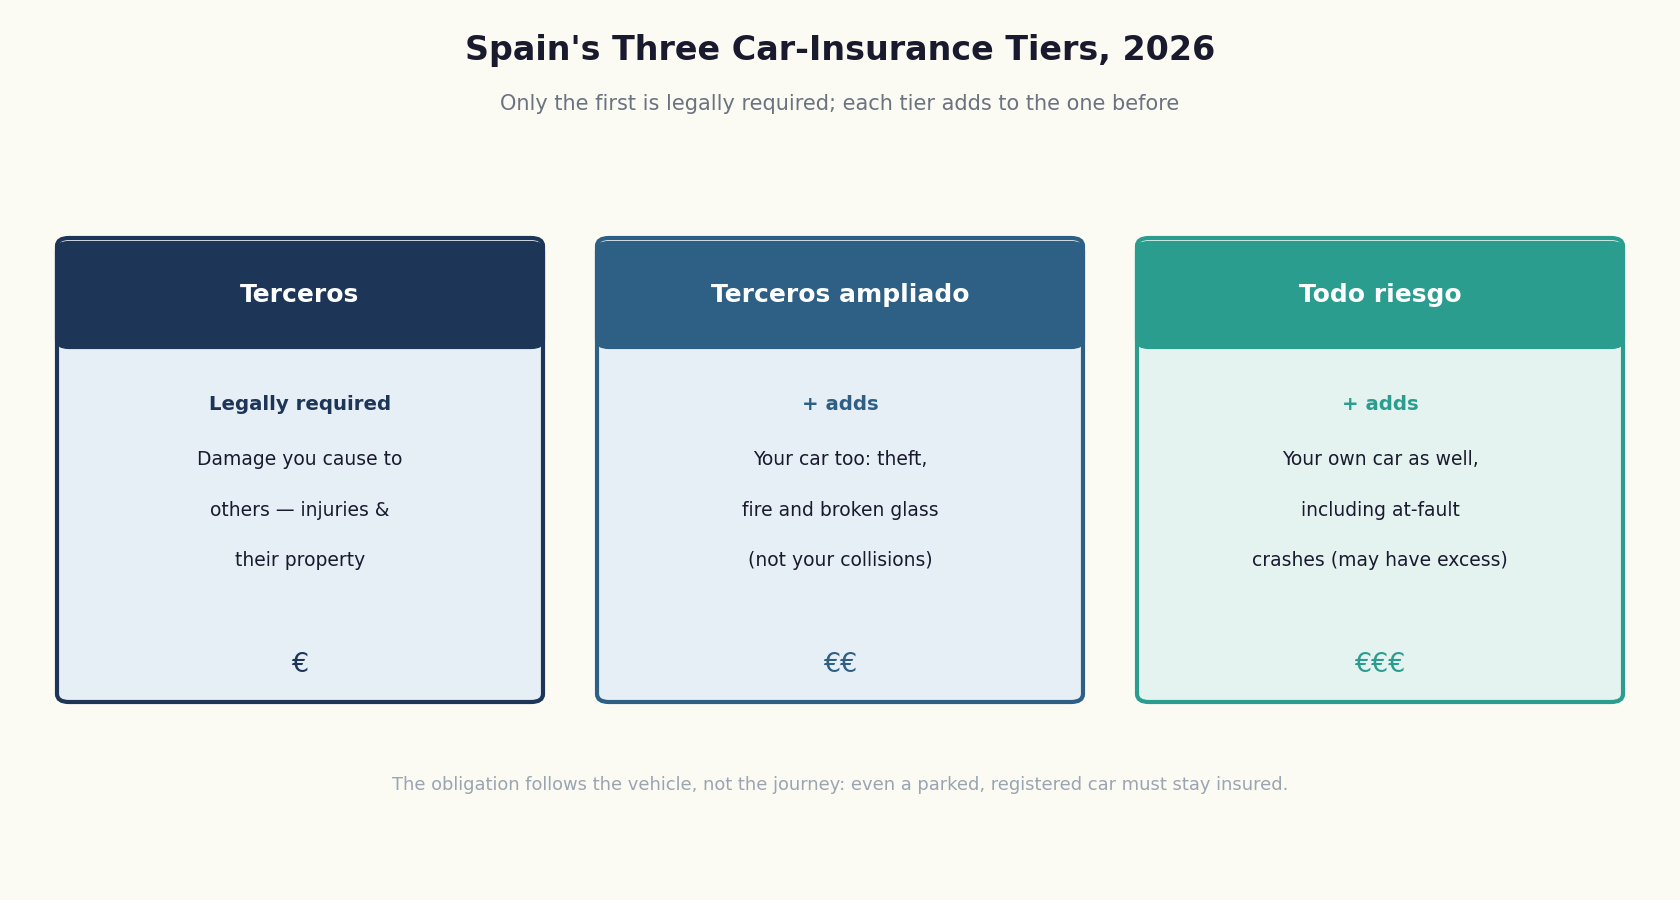
Only the first level is legally required, but the right choice depends on the age and value of your car and how much financial risk you are willing to carry yourself.
What It Costs
Motor insurance in Spain is, by European standards, relatively affordable, though prices vary widely by driver profile, vehicle, and region. As a rough order of magnitude, basic third-party cover commonly starts somewhere in the low hundreds of euros a year for a low-risk profile, third-party plus typically sits a step above that, and fully comprehensive policies start higher again and rise substantially with the value of the car. These are broad ranges rather than quotes: pricing changes every year and varies enormously by insurer, so the only figure worth acting on is a personalised quote for your own profile and postcode.
Several factors move the premium up or down: your age and how long you have held a licence, your Spanish claims history (there is a bonus-malus system rewarding claim-free years), the vehicle’s make, value, and power, where the car is habitually kept and parked, and your estimated annual mileage. Newcomers should be aware of a specific friction point: many Spanish insurers do not automatically recognise a no-claims history built up abroad, so a driver with decades of claim-free driving in another country may initially be quoted as a higher-risk new customer. It is worth asking whether an insurer will accept a certificate of your foreign claims record, as some will apply a discount if you can document it.
One practical note for foreign residents: to take out a Spanish policy you will generally need your NIE, a Spanish address, and, in most cases, a Spanish bank account for the direct debit, and many insurers will ask you to have exchanged your licence for a Spanish one once you are a resident. If you have not yet done that, our guide to exchanging your foreign driving licence in Spain explains the process and the strict six-month deadline that applies. You will also need your NIE and residence documents in place first; see our guide to the NIE, TIE, and empadronamiento.
How Enforcement Works: The FIVA Register
Spain enforces compulsory insurance through an automated database, the Fichero Informativo de Vehículos Asegurados (FIVA), maintained by the Consorcio de Compensación de Seguros. Insurers transmit data to it daily, and for each vehicle the file holds four things: the registration plate, a code identifying make and model, and the start and end dates of the current period of cover. It contains no personal data about the owner or driver at all.
FIVA has two purposes, and it is worth separating them. The first is enforcement, described below. The second is that after an accident it lets you find out who insures the other vehicle. That said, it is not a public lookup: access is restricted to people who were involved in a collision and suffered injury or damage, and the request is made on a set form accompanied by a copy of the accident report or the declaración amistosa. You cannot check a car before buying it this way, and the Consorcio does not answer these queries by telephone.
The practical consequence is that enforcement no longer depends on being pulled over. Police and DGT systems, including roadside cameras and automatic number-plate recognition, can cross-check a plate against FIVA in real time and detect an uninsured vehicle without any traffic stop at all. Since 2008, drivers are no longer even required to carry the paper policy or receipt in the car, precisely because the authorities can verify insurance status electronically from the plate alone. This is why “driving without insurance for just a few days” is far riskier than it sounds: detection can be entirely passive.
The Penalties for Driving, or Owning, Without Insurance
Driving without the compulsory policy is an administrative offence, not a criminal one, which means, perhaps surprisingly, that it does not cost you any points on your licence. But the financial and practical consequences are serious.
- The fine ranges from €601 to €3,005, graduated according to the type of vehicle, whether it was moving or parked, how long it had been uninsured, and whether the owner is a repeat offender. For an ordinary car, the fine typically lands around €1,500 when caught in circulation, with a lower figure commonly cited for a car merely parked while uninsured. Heavy or professional vehicles sit at the top of the scale.
- The vehicle can be immobilised or impounded until the owner proves a policy has been taken out. This immobilisation can last up to one month, extending to three months for repeat offenders, with all depot and towing costs charged to the owner.
- Prompt-payment discount. As with most Spanish administrative fines, paying within the roughly 20-day early window generally halves the amount, so a €1,500 fine can drop to €750 if not contested. Contesting the fine forfeits this discount.
Because the obligation falls on the owner, the fine is generally issued to the registered owner even if someone else was driving, and even if the car was only parked. Ownership, not use, is what the law tracks.
The Real Danger: An Accident While Uninsured
The fine is not the worst-case scenario. If you cause an accident while uninsured, the financial exposure can be catastrophic, and this is where the true purpose of the system becomes clear.
When an uninsured vehicle causes harm, the victims are not left unprotected: the Consorcio de Compensación de Seguros (CCS), a state-backed body that also compensates damage caused by unknown, uninsured or stolen vehicles, steps in to indemnify the injured third parties for their personal and material damage within the compulsory-insurance limits. But that is not the end of the story for the uninsured driver. The Consorcio then exercises its derecho de repetición, its right of recovery, and reclaims from the responsible owner and driver the full amount it has paid out. In other words, the victim is protected, but the uninsured party ultimately foots the entire bill, which in a serious injury case can run to hundreds of thousands of euros, enforceable against their personal assets. This is why treating compulsory insurance as an optional cost to skip is a false economy of the most dangerous kind.
New for 2026: E-Scooters and Personal Mobility Vehicles Now Need Insurance Too
This is the change most likely to catch out city-dwelling newcomers, because it is recent and because many people simply do not think of an e-scooter as a vehicle in the insurance sense.
Spain’s Ley 5/2025 of 24 July, which transposes EU Directive 2021/2118 on motor insurance, extended the compulsory civil liability requirement to personal mobility vehicles (VMP). Real Decreto 52/2026 of 28 January then supplied the missing machinery, creating the Registro de Vehículos Personales Ligeros within the DGT’s national vehicle register and setting out how inscription and the identification label work.
Start with whether your device is legally a VMP at all, because the definition is narrower than most people assume. The DGT defines a VMP as a vehicle with one or more wheels, a single seat, propelled exclusively by electric motors, with a maximum speed of between 6 and 25 km/h. Below 6 km/h it is not a VMP; above 25 km/h it is not a VMP either, and that upper limit has consequences covered below. To circulate, a VMP must hold a certificate of circulation issued by a DGT-authorised laboratory, be inscribed in the register, and carry its identification label.
There is one deadline that matters more than any other and that most coverage buries. If your scooter is not a certified model, you can still inscribe it temporarily, but the DGT states that such a certificate is valid only until 22 January 2027. After that date an uncertified device cannot legally be used on public roads at all. If you own a scooter bought before the certification regime, or are thinking of buying second-hand, check it against the DGT’s published list of certified models before you pay, because a device that cannot be certified becomes an ornament in January 2027.
Three practical points matter most:
- Pedal-assist e-bikes are exempt. Standard EPAC electric bicycles that comply with the norm (motor assistance cutting out at 25 km/h, within the power limit) are not VMP and do not need this insurance. Higher-powered e-bikes with a throttle that propels the bike without pedalling generally do fall within scope.
- A household or general liability policy does not count. The requirement is for a specific motor civil liability policy meeting the statutory conditions, not the incidental cover in a home insurance package.
- Exceed the limits and it stops being a VMP entirely. A device capable of more than 25 km/h, or above the permitted power, is legally treated as a moped (ciclomotor), which means registration plates, a driving licence, and full motorcycle insurance. This is a different legal category, not a grey area, and it catches out people who buy a powerful imported scooter.
Be careful with dates you read elsewhere on this. The obligation was phased in through 2026 in stages that depended on the weight and speed of the device and on the register becoming operational, and published summaries disagree with each other about which date applies to what, some citing early January and others the end of the month. That disagreement is itself the reason to go to the source: confirm the requirements for your specific device with the DGT’s electronic office, which handles inscription, transfer and deregistration of a VMP online, rather than relying on any summary, including this one. The underlying principle, though, is the same one that governs cars: if you injure someone and you are uninsured, the compensation ultimately comes out of your own pocket.
A Note on Bringing a Foreign Car to Spain
If you import a vehicle when you move, the insurance clock is linked to registration. Once your car becomes habitually based in Spain and is registered here, the Spanish compulsory-insurance obligation applies in full, and a foreign policy will generally not satisfy it beyond an initial transitional period. Coordinating the vehicle’s re-registration, roadworthiness test (ITV), and Spanish insurance is part of the wider import process; our guide to moving vehicles, pets, and belongings to Spain covers the registration and tax steps that run alongside insuring the car.
Frequently Asked Questions
Do I need to insure a car I never drive?
Yes, if it is registered with the DGT, even if it stays in a private garage. The only way to lawfully avoid insuring it is to process a baja temporal or baja definitiva, and while on baja temporal the car cannot be parked on or driven on public roads.
Does the compulsory insurance cover any driver, or just me?
The compulsory civil liability cover attaches to the vehicle, so in principle any licensed driver you permit to use it is covered for third-party liability. Be careful, though: optional cover tiers (fully comprehensive, or policies with a named/authorised driver clause) can exclude drivers who are not listed, so check your specific policy before lending the car.
Will I lose licence points for driving uninsured?
No. Unlike speeding, drink-driving, or phone use, driving without insurance does not carry a points penalty, because it is an administrative rather than a traffic-safety offence. The consequences are purely financial and administrative: the fine, and possible immobilisation of the vehicle.
I just moved to Spain. Can I keep driving on my foreign insurance?
Only for a limited transitional period, and only while the vehicle’s habitual base has not yet shifted to Spain. Once you are resident and the car is based here, you need a Spanish-compliant policy, and typically a Spanish-registered vehicle. Do not assume a foreign policy indefinitely satisfies the Spanish obligation.
Does my electric scooter really need its own insurance?
If it is a personal mobility vehicle used on public roads, yes, since the 2026 reform. Standard pedal-assist e-bikes within the legal limits are exempt, but scooters and similar motorised devices now require a specific civil liability policy, and a home insurance policy does not satisfy the requirement. Check your particular device against the DGT’s current criteria.
Still getting set up after your move? Our full guide to moving to Spain in 2026 covers the residency, licence, and vehicle steps that typically come together in the first few months.
Verified August 2026 against Royal Legislative Decree 8/2004 as published in the Boletín Oficial del Estado; the DGT’s guidance on personal mobility vehicles and its electronic office pages for VMP inscription and deregistration; and the Consorcio de Compensación de Seguros on the FIVA register and its role in compensating damage caused by uninsured vehicles. The VMP framework introduced by Ley 5/2025 and Real Decreto 52/2026 is still being phased in and published summaries disagree on the applicable dates, so confirm the position for your own device with the DGT before relying on it.
This article is for general informational purposes only and does not constitute legal or insurance advice. Insurance requirements, fine amounts, and enforcement procedures change and depend on your specific vehicle, circumstances, and region; the rules for personal mobility vehicles in particular were introduced recently and are still being phased in. Prices cited are indicative and vary by insurer and driver profile. Before insuring or deregistering a vehicle, confirm the current rules with the DGT and a licensed Spanish insurer, and consult a professional about your individual situation.