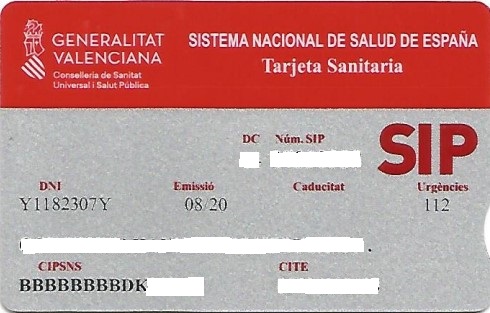
Of all the documents in a Spanish Digital Nomad Visa (DNV) application, the one most likely to get your file rejected is not your contract, your income proof, or your background check. It is your health insurance policy. Spanish consulates and the immigration unit that processes these visas have grown notably stricter, and the single most common rejection trigger is a policy that contains a copayment, a waiting period, or comes from an insurer not authorised to operate in Spain.
This guide explains exactly what a “zero-copay” policy means, why it matters so much, what to look for when comparing insurers, and the traps that quietly sink otherwise strong applications. The goal is simple: to help you buy the right policy once, rather than discover the problem when your visa comes back denied.
Why Health Insurance Is the DNV’s Hidden Hurdle
The Digital Nomad Visa, created under Spain’s Startup Act, lets non-EU remote workers, freelancers, and entrepreneurs live in Spain while working primarily for clients or employers based outside the country. It is generous in many ways, but the health-insurance rule is rigid, because Spain wants proof that you will never become a burden on its public system and will have immediate access to care from day one.
In practice, the authorities are checking your policy certificate against a short list of legal requirements. If a required element is missing, or a prohibited feature appears, the application can be rejected. The certificate, not the glossy brochure, is what gets read.
The Four Pillars of a Visa-Compliant Policy
These conditions are not consular folklore. The visa itself exists under Article 74 bis of Law 14/2013 on support for entrepreneurs and their internationalisation, which is the provision that defines a teleworker of international character, and the requirements are published by the Ministry of Inclusion, Social Security and Migration through the unit that processes these files. Its page for teleworkers of international character sets out the documentation and links the official applicant guidance in both Spanish and English. Read it alongside the requirements published by the consulate handling your application, since consulates differ on points of detail while the underlying rule does not.
The ministry states the health-insurance condition in terms worth quoting closely, because the negatives are what decide files: cover must come either from public insurance through Social Security registration or from equivalent private insurance arranged with an insurer authorised to operate in Spain, and travel policies are not valid, nor are policies limited to the reimbursement of medical expenses, nor any policy carrying waiting periods or copayments.
To pass review in 2026, your policy must therefore satisfy four core conditions.

1. An insurer authorised to operate in Spain. The carrier must be registered with Spain’s insurance regulator, the DGSFP (Dirección General de Seguros y Fondos de Pensiones). This is the requirement that disqualifies most travel and “nomad” insurance. Travel-style plans and global expat products are frequently rejected for long-stay residence visas, even when their coverage limits are far higher than a Spanish plan, simply because they are not Spanish-authorised resident policies. You can check any insurer’s registration directly on the DGSFP’s public register rather than taking a salesperson’s word for it.
2. Full coverage equivalent to the public system (Seguridad Social). The policy must match what Spain’s public healthcare covers: GP visits, specialist consultations, diagnostic tests, hospitalisation, surgery, and emergencies. Repatriation coverage is also commonly expected and, at some consulates, treated as mandatory.
3. No copayments (“sin copagos”). This is the heart of the matter. Many standard Spanish health plans charge a small fee per visit, perhaps €5 to €15 for a GP appointment. Those reduce the monthly premium, but they are an automatic ground for rejection. Your policy must cover 100% of costs at the point of service, with nothing out of pocket. Even a token copay can fail.
4. No waiting periods (“sin carencias”) and no coverage cap. Standard private policies often impose waiting periods of several months before you can access surgery, complex imaging, or other treatments. A visa-compliant policy must waive these so coverage is effective immediately. The certificate must also show no monetary limit on hospital, outpatient, or specialist treatment.
On top of these, the policy generally must be valid for the full visa period (typically purchased and paid 12 months upfront), and the certificate (the certificado de seguro médico) should be issued in Spanish. Most consulates want a formal certificate, not an insurance card or an app screenshot.
The “Copay Trap” That Catches First-Time Applicants
Here is the subtlety that trips up so many people: the major Spanish insurers all sell visa-compliant, no-copay policies, but those are usually not the products you see advertised on their retail websites. The plans marketed to the general public, and the ones bank branches bundle into accounts, almost always include copays and waiting periods. They are cheaper, which is exactly why they exist, and exactly why they fail consular review.
The visa-compliant, zero-copay versions are typically arranged through insurance brokers who understand the immigration requirements. A good broker confirms you receive the no-copay tier with immediate coverage, issues the certificate in the format and language the consulate expects, and lists every dependent correctly. The broker is usually paid by the insurer, so this expertise normally costs you nothing extra. Buying directly from a sales rep who does not understand visa nuances is one of the most common ways applicants end up with a non-compliant policy.
The Insurers That Come Up Most Often
A handful of Spanish carriers appear repeatedly in approved DNV files. The notes below summarise how each is generally positioned in the market, to give you a starting point for your own comparison. This site has no commercial relationship with any insurer and has not independently tested these policies, so treat this as orientation rather than a recommendation, and verify every detail directly with the carrier or a licensed broker before buying.
- Adeslas is Spain’s largest private health insurer, with the widest hospital and clinic network in the country, which tends to mean shorter specialist waits and decent coverage in rural areas. It is often among the more affordable visa-compliant options for younger applicants. Its main constraint is age: new enrolment is generally capped around 65, with older applicants considered case by case after medical review.
- Sanitas is owned by the UK’s Bupa group and is frequently mentioned by expats who prioritise English-language support. It runs its own hospitals and clinics and has a strong telemedicine offering. It typically prices above Adeslas for comparable cover.
- DKV, part of the ERGO/Munich Re group, has a reputation for being relatively accommodating on pre-existing conditions and for accepting older applicants than Adeslas, though limits vary by plan. Its network is strongest in eastern Spain, including Barcelona, Valencia, and Mallorca, and thinner in the south and northwest.
- Asisa is a long-established, physician-owned medical cooperative known for straightforward, competitively priced plans, with a nationwide network that is strong in Madrid, Valencia, Andalusia, and Murcia. English-language support is more limited.
- ASSSA is known for accepting older applicants and for flexible underwriting around pre-existing conditions. Most digital nomads will not need it, but for an older applicant or a complex medical history it is often the more realistic route to a compliant policy.
- Feather is an expat-focused, digital-first insurer that issues certificates in both Spanish and English online. It is worth comparing its provider network against the established carriers for the specific city where you will live.
Whichever you consider, confirm the carrier’s DGSFP registration yourself and confirm in writing that the specific product quoted is the no-copay, no-waiting-period tier.
What Visa-Compliant Cover Costs
Premiums are driven mainly by your age at enrolment, then by carrier, location, and coverage tier. As a rough order of magnitude, a healthy adult in their twenties or thirties on a no-copay, visa-compliant plan can generally expect a monthly premium somewhere in the region of €40 to €85, rising substantially with age, with applicants in their mid-fifties commonly quoted roughly double that. These are broad ranges, not quotes: insurance pricing changes every year and varies by city, so the only figure that means anything is a personalised quote for your own age and postcode.
A few practical notes on cost. Major cities such as Madrid, Barcelona, and Valencia tend to price similarly for the same plan, while smaller cities and rural areas can be somewhat cheaper, sometimes with a thinner local network. Family applications usually attract a modest discount versus separate individual policies, and each applicant still needs their own compliant certificate. For visa purposes, expect to pay the full year upfront; monthly billing typically becomes available only at renewal.
The Limits Even a “Full Coverage” Policy Has
“No copay, no limits” describes the visa requirement, not unlimited everything. It is worth knowing what these policies typically do not cover, so there are no surprises once you are living in Spain.
- Outpatient prescription medication is generally not covered by Spanish private insurance; you pay for pharmacy prescriptions yourself, whereas the public system subsidises them.
- Maternity is subject to a waiting period with most carriers, commonly in the region of eight to ten months from the policy start, so a pregnancy that begins before that window is excluded. If you are planning a family, plan a year ahead and confirm the exact period in your policy wording.
- Dental is usually a separate add-on rider, with only basic check-ups included in some plans.
- Pre-existing conditions that you declare may be excluded for an initial period, depending on the insurer and severity. Be honest on the application: undisclosed conditions can void the policy when you most need it.
Switching to Public Healthcare Later
For your initial DNV application you must hold private insurance, because you do not yet have residency or a Social Security number. However, many digital nomads register as autónomo (self-employed) in Spain for tax reasons, and once you are contributing to Social Security you gain access to the public health system (SNS).
The cost of that route is worth understanding properly, because it is frequently misstated. Autónomo contributions run on an income-based system of fifteen brackets, and the 2026 quotas were frozen at 2025 levels: the minimum monthly quota runs from roughly €199 at the lowest bracket to about €588 at the highest, depending on your declared net earnings. Those figures come from Orden PJC/297/2026, whose Article 18 sets the contribution bases for the year, applied at the 2026 rate of 30.50%. Crucially for anyone registering for the first time, the tarifa plana remains in force at €80 per month for the first 12 months, extendable to 24 months where income conditions are met. A newly registered digital nomad will therefore normally be paying €80, not a figure in the hundreds, during their first year. Our guide to registering as an autónomo or setting up an SL covers the process and the brackets in detail.
At your visa renewal, you may be able to rely on Social Security instead of private insurance. In practice, plenty of residents keep both: public cover for its pension and prescription benefits, plus a cheaper private plan for faster specialist access and English-speaking doctors. For a full comparison of how the public system, the convenio especial, and private cover fit together, see our guide to public healthcare vs. private insurance in Spain.
How to Get the Right Policy, Step by Step
- Contact a specialist broker or a visa-focused insurer and state clearly that you are applying for the Digital Nomad Visa.
- Request the no-copay, no-waiting-period tier explicitly, and confirm the certificate will say sin copagos and sin carencias with no coverage cap.
- Verify the insurer’s DGSFP registration yourself on the regulator’s public register.
- Compare at least two or three carriers, since price varies widely by age and city; the broker service is normally free to you.
- Pay the first 12 months upfront and obtain the official certificado in Spanish, which usually takes a few business days.
- Check the start date. The policy must be active when the visa is issued; a start date that is too late can cause a rejection.
- Submit the original certificate with your other documents, ensuring all dependents are listed.
How to Decide
Rather than looking for the single “best” insurer, work through the variables that actually determine the right fit for you. Your age at enrolment drives both price and eligibility, and is the single largest factor. The city where you will live determines which networks are genuinely strong near you, which matters more than headline network size. How much you value English-language service is a real trade-off against price. And any pre-existing condition narrows the field considerably, since carriers differ substantially in how they underwrite them.
Whatever you choose, the rule that protects your application is the same: a Spanish-authorised insurer, full coverage, zero copays, zero waiting periods, no limit, and a certificate in Spanish. Get that combination right, and what is usually the most fragile part of a DNV file becomes one of the simplest. For the wider sequence of the move, see our overview of how to move to Spain in 2026.
Verified August 2026 against the requirements published by the Ministerio de Inclusión, Seguridad Social y Migraciones for teleworkers of international character under Article 74 bis of Law 14/2013, against the public register and guidance of the Dirección General de Seguros y Fondos de Pensiones (DGSFP), and against Orden PJC/297/2026, de 30 de marzo, as published in the Boletín Oficial del Estado of 31 March 2026, for the autónomo contribution bands. This article is for general informational purposes only and does not constitute insurance, legal, or financial advice. This site has no commercial relationship with any insurer mentioned and receives no commission. Insurance products, prices, age limits, and consular requirements change frequently and can vary by consulate and by your individual circumstances. Verify current plan details directly with the insurer or a licensed Spanish insurance broker, and confirm the exact requirements with the relevant Spanish consulate or immigration office before purchasing a policy or submitting your application.